Ankur Warikoo Shares 5 Money Rules for People in Their 40s, From Investing First to Spending on Experiences
Entrepreneur and personal finance educator Ankur Warikoo has shared five financial principles that he and his wife, Ruchi, follow while raising their ...
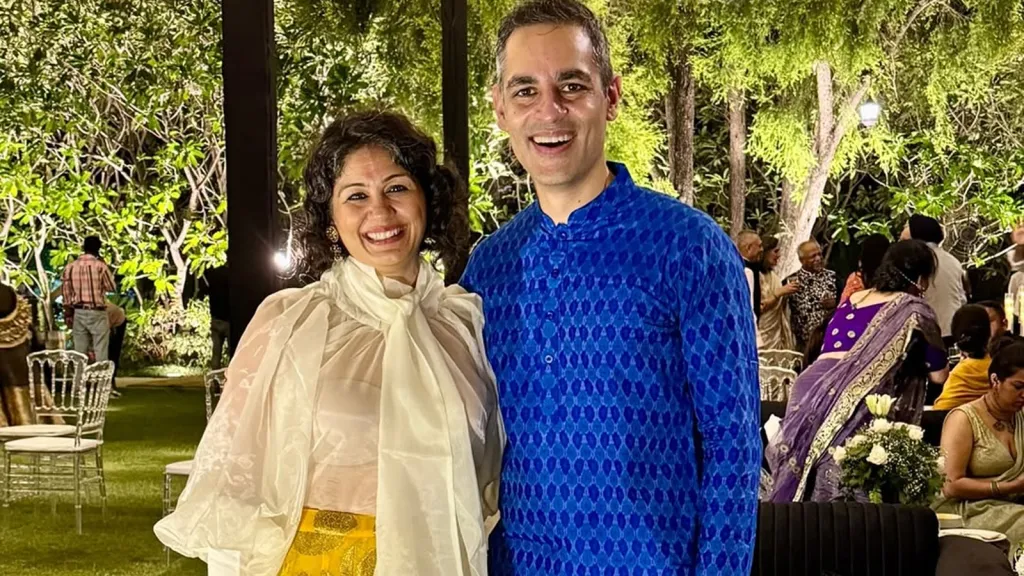
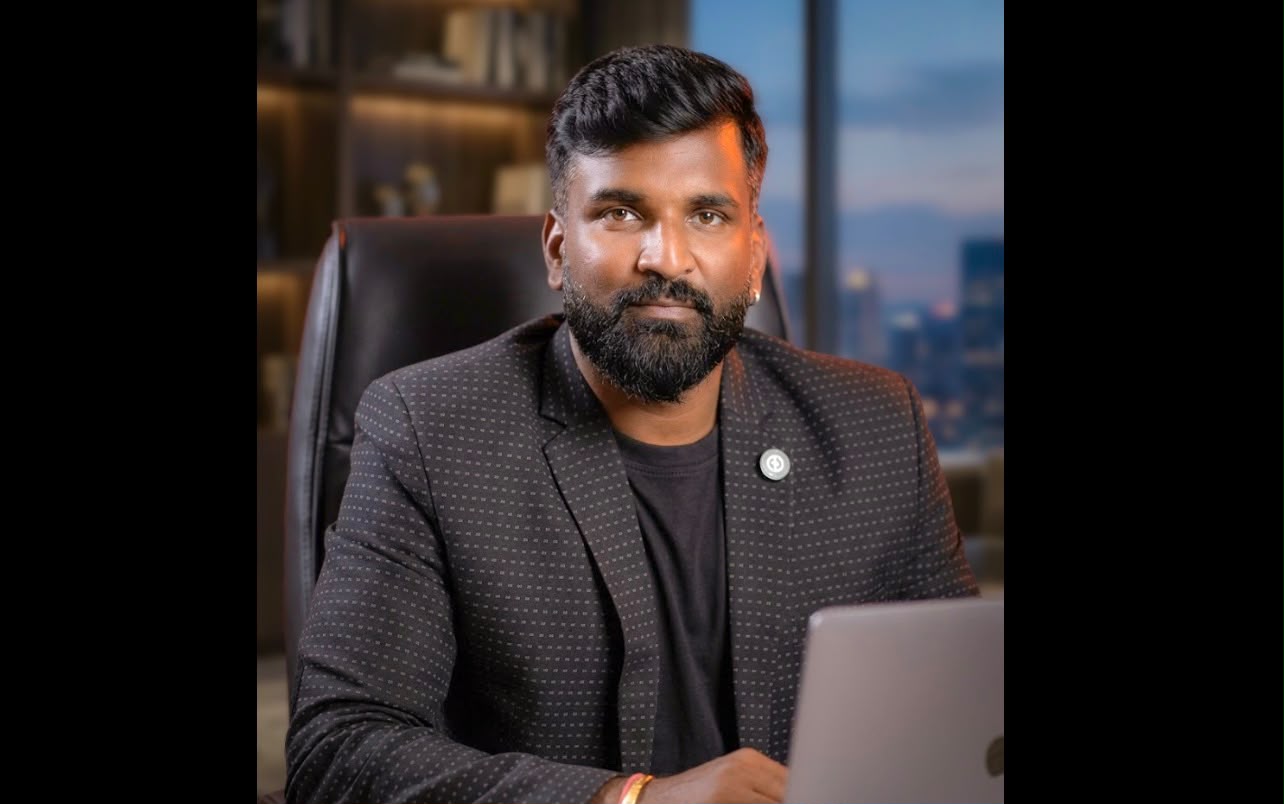
Entrepreneur and personal finance educator Ankur Warikoo has shared five financial principles that he and his wife, Ruchi, follow while raising their two children. Their approach focuses on building long-term financial security, spending thoughtfully and making room for experiences and continuous learning rather than using money to maintain an expensive lifestyle.
At 45, Warikoo says the couple's financial decisions are guided by their priorities rather than social expectations. Their rules cover everything from investment habits and everyday spending to food, travel and education. The broader message is that managing money effectively involves deciding what matters most, not simply trying to earn more or cut every expense.
The couple's approach offers a perspective on financial planning during one's 40s, a stage when household expenses, children's needs and preparation for retirement may all compete for attention.
1. Build wealth instead of trying to look wealthy
One of the couple's central principles is to avoid spending primarily to impress other people. Expensive brands, luxury purchases and possessions acquired for social recognition can consume money without necessarily improving long-term financial stability.
Warikoo and Ruchi say they prefer directing money towards assets and investments that can support future financial independence. They own the home they live in, while choosing to rent a car rather than purchase one.
Their philosophy challenges the assumption that visible signs of wealth always indicate financial success. A person may own expensive possessions while carrying substantial debt, whereas someone with a simpler lifestyle may be building a stronger financial foundation.
The underlying lesson is to evaluate purchases according to personal needs and long-term goals instead of comparing lifestyles with friends or social media personalities.
2. Give priority to good-quality food
The couple also places considerable importance on the quality of the food they eat. Their reasoning is that health is a long-term priority, making food an area where they are comfortable spending more when their budget allows.
This does not mean that expensive food is automatically healthier. Rather, the principle is to make informed choices about nutrition and avoid treating every essential expense as an opportunity to cut costs.
For households managing several financial responsibilities, the approach encourages a distinction between unnecessary luxury spending and expenses that contribute meaningfully to everyday well-being.
3. Spend on experiences, not just possessions
Travel and shared experiences are another priority for Warikoo and his family. Their approach places value on activities that create memories and allow family members to explore new places and interests together.
Material purchases can provide convenience or enjoyment, but the couple believes experiences deserve a place in the household budget as well.
This principle does not require families to spend beyond their means on holidays. Affordable outings, local travel and activities enjoyed together can also create meaningful experiences. The important point is to allocate money intentionally rather than directing it automatically towards possessions.
4. Invest before paying for everyday wants
Warikoo advocates making investments a priority when income arrives, rather than waiting to see what remains after spending.
Under this approach, a planned amount is allocated towards financial goals first, with the remaining money used for regular expenses. This can help create consistency and reduce the temptation to spend money that was intended for the future.
However, the appropriate amount to invest depends on individual circumstances. Essential expenses, emergency savings and suitable insurance should be considered before committing money to investments. Investments also carry varying levels of risk, so choices should reflect a person's goals and time horizon.
5. Keep learning throughout life
The couple's final rule is to avoid placing an unnecessarily strict limit on books and learning opportunities. They see education as an ongoing activity rather than something that ends with formal schooling.
Reading, acquiring new skills and exploring unfamiliar subjects can contribute to personal development and open up future opportunities. For children and adults alike, a habit of learning can be valuable across different stages of life.
The principle does not mean ignoring financial limits. Instead, it encourages households to make room for worthwhile educational spending alongside their other priorities.
A personal approach to financial planning
Warikoo's five rules are based on the choices he and his wife make for their family, rather than a universal formula for managing money. Every household has different income levels, responsibilities and financial goals.
The broader takeaway is to create a plan that reflects those circumstances: invest consistently where appropriate, protect against financial risks, spend deliberately and avoid measuring success through appearances alone. Over time, clear priorities can help families make more confident decisions about both their money and their future.Entrepreneur and personal finance educator Ankur Warikoo has shared five financial principles that he and his wife, Ruchi, follow while raising their two children. Their approach focuses on building long-term financial security, spending thoughtfully and making room for experiences and continuous learning rather than using money to maintain an expensive lifestyle.
At 45, Warikoo says the couple's financial decisions are guided by their priorities rather than social expectations. Their rules cover everything from investment habits and everyday spending to food, travel and education. The broader message is that managing money effectively involves deciding what matters most, not simply trying to earn more or cut every expense.
The couple's approach offers a perspective on financial planning during one's 40s, a stage when household expenses, children's needs and preparation for retirement may all compete for attention.
1. Build wealth instead of trying to look wealthy
One of the couple's central principles is to avoid spending primarily to impress other people. Expensive brands, luxury purchases and possessions acquired for social recognition can consume money without necessarily improving long-term financial stability.
Warikoo and Ruchi say they prefer directing money towards assets and investments that can support future financial independence. They own the home they live in, while choosing to rent a car rather than purchase one.
Their philosophy challenges the assumption that visible signs of wealth always indicate financial success. A person may own expensive possessions while carrying substantial debt, whereas someone with a simpler lifestyle may be building a stronger financial foundation.
The underlying lesson is to evaluate purchases according to personal needs and long-term goals instead of comparing lifestyles with friends or social media personalities.
2. Give priority to good-quality food
The couple also places considerable importance on the quality of the food they eat. Their reasoning is that health is a long-term priority, making food an area where they are comfortable spending more when their budget allows.
This does not mean that expensive food is automatically healthier. Rather, the principle is to make informed choices about nutrition and avoid treating every essential expense as an opportunity to cut costs.
For households managing several financial responsibilities, the approach encourages a distinction between unnecessary luxury spending and expenses that contribute meaningfully to everyday well-being.
3. Spend on experiences, not just possessions
Travel and shared experiences are another priority for Warikoo and his family. Their approach places value on activities that create memories and allow family members to explore new places and interests together.
Material purchases can provide convenience or enjoyment, but the couple believes experiences deserve a place in the household budget as well.
This principle does not require families to spend beyond their means on holidays. Affordable outings, local travel and activities enjoyed together can also create meaningful experiences. The important point is to allocate money intentionally rather than directing it automatically towards possessions.
4. Invest before paying for everyday wants
Warikoo advocates making investments a priority when income arrives, rather than waiting to see what remains after spending.
Under this approach, a planned amount is allocated towards financial goals first, with the remaining money used for regular expenses. This can help create consistency and reduce the temptation to spend money that was intended for the future.
However, the appropriate amount to invest depends on individual circumstances. Essential expenses, emergency savings and suitable insurance should be considered before committing money to investments. Investments also carry varying levels of risk, so choices should reflect a person's goals and time horizon.
5. Keep learning throughout life
The couple's final rule is to avoid placing an unnecessarily strict limit on books and learning opportunities. They see education as an ongoing activity rather than something that ends with formal schooling.
Reading, acquiring new skills and exploring unfamiliar subjects can contribute to personal development and open up future opportunities. For children and adults alike, a habit of learning can be valuable across different stages of life.
The principle does not mean ignoring financial limits. Instead, it encourages households to make room for worthwhile educational spending alongside their other priorities.
A personal approach to financial planning
Warikoo's five rules are based on the choices he and his wife make for their family, rather than a universal formula for managing money. Every household has different income levels, responsibilities and financial goals.
The broader takeaway is to create a plan that reflects those circumstances: invest consistently where appropriate, protect against financial risks, spend deliberately and avoid measuring success through appearances alone. Over time, clear priorities can help families make more confident decisions ab
Related Stories
Reader comments are moderated as per Daily News Axis editorial standards.